News Made Clear · Loading…
Category
Regions
Continents
Dutch savings total masks differences in households’ ability to invest
Loading statistics…
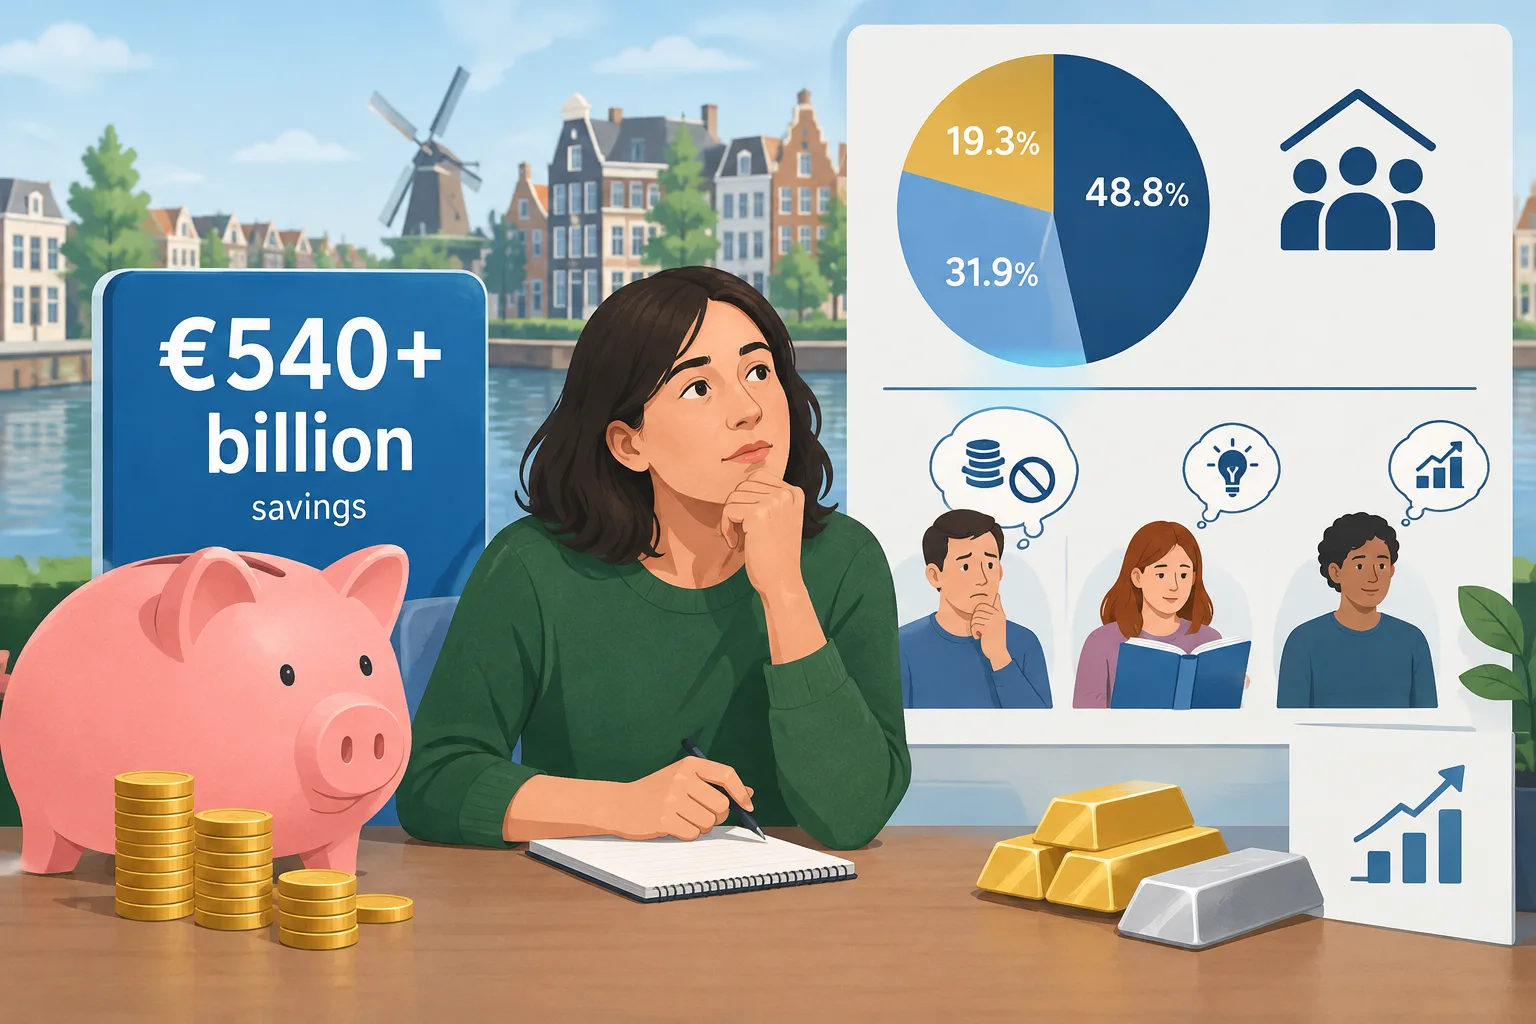
Dutch households collectively held more than €540 billion in savings in March 2026, but that total does not show who has money available to invest.
Review information is loading.
Nieuws.nl reported on Wednesday that, according to Cleverr, a lack of money rarely explains why people do not invest. Cleverr sells physical gold and silver and has also made the claim on its own website.
An AFM survey gives a more complicated picture. In April 2024, about a third of 605 non-investors whose responses were linked to household data said they had no money to invest. Lack of knowledge was the most frequently cited reason; respondents could give more than one answer. The survey does not show how often a lack of money was the decisive factor.
A separate AFM analysis of official household data found that 48.8% of all Dutch households had no investments under its definition and had less liquid wealth than their recommended Nibud buffer in 2024. Another 31.9% had no such investments but did have wealth above the buffer. The recommended amount varies by household and is intended to cover unexpected expenses.
Those figures describe households’ finances, not their reasons for investing or holding back. The analysis counted investments subject to the Dutch ‘box 3’ wealth tax, but excluded individual pension investments.
A different AFM survey estimated that 26% of households had at least one person who invested in July 2025. That survey included individual pension investments and financial crowdfunding, but excluded investments through employer pension funds and cryptocurrencies. Its definition and date mean it cannot be directly compared with the 2024 figures.
Savings platform Raisin reported that Dutch households held more than €540 billion in savings at banks in the Netherlands in March 2026, citing central bank figures. About €451 billion was readily accessible. The total does not show how savings are distributed or how much each household can spare for the long term.
The AFM also identified roughly 822,000 non-investing households with wealth above their buffer whose projected state and workplace pensions were below 70% of their current income. This was a narrower group, with a main earner and any partner aged 35 to 67 and not retired. The calculation excluded personal pensions and other assets, so it was not a complete assessment of their retirement finances.
The regulator says investing can offer higher long-term returns than saving, but carries greater risk. It advises investing only money that can be left untouched for the long term.
How do we know?
6 listed sources · explore evidence, limitations and provenance.
Sign in to give this article a thumbs up or down.
About this discussion and AI questions
Private test discussion. Comments are readers’ views and are not yet automatically fact-checked. Editing is available for 60 seconds after posting.
Sign in with a confirmed reader account and choose a username to read comments and participate.
Sorting applies to top-level comments; replies remain oldest first. New comments and likes can change the order. Refresh for the current ranking.
Loading comments…